
Advertorial or Sponsorship User published Content does not represent the views of the Company or any individual associated with the Company, and we do not control this Content. In no event shall you represent or suggest, directly or indirectly, the Company's endorsement of user published Content.
The company does not vouch for the accuracy or credibility of any user published Content on our Website and does not take any responsibility or assume any liability for any actions you may take as a result of reading user published Content on our Website.
Through your use of the Website and Services, you may be exposed to Content that you may find offensive, objectionable, harmful, inaccurate, or deceptive.
By using our Website, you assume all associated risks.This Website contains hyperlinks to other websites controlled by third parties. These links are provided solely as a convenience to you and do not imply endorsement by the Company of, or any affiliation with, or endorsement by, the owner of the linked website.
Company is not responsible for the contents or use of any linked website, or any consequence of making the link.
DHI Mortgage Reviews and Ratings
DHI Mortgage logo
DHI Mortgage is a licensed, operating lender. It is also the in-house lender for D.R. Horton. Most readers searching for DHI Mortgage reviews are weighing a D.R. Horton home and a decades-long loan.
So, is DHI Mortgage legit? This DHI Mortgage review breaks down the lender’s rates, fees, ratings, and what buyers should verify before signing.
What is DHI Mortgage?

DHI Mortgage website homepage
DHI Mortgage Company, Ltd. (NMLS #14622) is the wholly owned mortgage lender of D.R. Horton, Inc., the largest U.S. homebuilder. It provides mortgage financing mainly to people buying a D.R. Horton home.
The company is based at 10700 Pecan Park Blvd., Suite 450, Austin, Texas. It works alongside sister companies DHI Title, D.R. Horton Insurance Agency, and DHI Title Insurance Company.
What a captive lender means
A captive lender is a wholly owned subsidiary that finances purchases from its parent company. DHI Mortgage fits this model as D.R. Horton’s financing arm.
Captive lenders are most common in the auto industry. Homebuilders use the same setup, pairing the home sale and the loan under one parent company.
This model can benefit buyers through easier approval or lower rates, since the parent controls both the sale and the loan. The downside is less pressure to shop around, since the builder’s lender is presented as the default option.
DHI Mortgage at a glance
- DHI Mortgage Company, Ltd. holds NMLS #14622.
- The lender is the in-house mortgage arm for D.R. Horton buyers.
- Headquarters are at 10700 Pecan Park Blvd., Suite 450, Austin, Texas.
- Affiliates include DHI Title, D.R. Horton Insurance Agency and DHI Title Insurance Company.
- Licensing covers more than 30 states, per its website.
- Loan volume reached 68,982 originated or brokered loans in fiscal year 2025.
- The company has a pending class action lawsuit.



DHI Mortgage products and services
DHI Mortgage keeps its lineup focused on home purchase loans, a credit-readiness program and online tools for buyers.
Home purchase financing for D.R. Horton buyers
DHI Mortgage offers conventional, FHA and VA loans to D.R. Horton buyers across its licensed states.
DHI Mortgage Home Buyers Club
The DHI Mortgage Home Buyers Club serves credit-challenged buyers preparing for homeownership.
A personal credit consultant analyzes the buyer’s credit profile and builds a plan to qualify for a mortgage. Members also complete a HUD-approved homebuyer education course at their own cost.
Joining does not require financing through DHI Mortgage or buying a D.R. Horton home. The club does not guarantee higher credit scores or loan approval.
Online tools and mortgage calculator
DHI Mortgage provides online tools to start the loan process. Buyers can estimate payments with its mortgage calculator and manage an active loan through the DHI Mortgage portal.
DHI Mortgage cost and fees
DHI Mortgage does not post a public rate sheet. State disclosures list origination charges of 0 percent to 1 percent of the loan amount plus a flat fee. These flat fees range from about $950 to $1,495, and processing fees add $250 to $300.
Certain affordable housing programs add 1 to 1.5 percent of the loan amount. Fees vary by state and by whether DHI Mortgage originates or brokers the loan. Buyers receive a full Loan Estimate of settlement charges within three business days of applying.
D.R. Horton ties incentives such as rate buydowns and closing-cost credits to financing through DHI Mortgage.
How your property tax estimate shapes your real payment
A monthly DHI mortgage payment covers more than principal and interest. Lenders add property taxes and homeowners insurance, then hold those funds in an escrow account until bills come due.
The quoted payment is built from an estimated property tax figure. New construction can start with a low pre-construction land value. The real tax bill arrives only after the home is assessed, and it is usually much higher.
Buyers should verify the home’s post-construction tax bill with the county assessor before relying on any quoted payment.
DHI Mortgage outcomes and success rate
DHI Mortgage does not publish origination totals or approval rates on its website. The company presents its scale through its tools and programs instead.
Its site highlights a mortgage calculator, online loan tools and the Home Buyers Club for credit-challenged buyers.
DHI Mortgage reviews and ratings
Customer reviews for DHI Mortgage skew negative across independent platforms. The figures below reflect data pulled in September 2026.
WalletHub reviews

DHI Mortgage WalletHub profile
DHI Mortgage holds a 2.2 rating on WalletHub from 77 reviews. About 66 percent of reviewers gave one star, while 26 percent gave five stars.
Common complaints name slow turnarounds, poor communication and repeated document requests. Several reviews describe closing delays that stretched for weeks.
Better Business Bureau (BBB) reviews
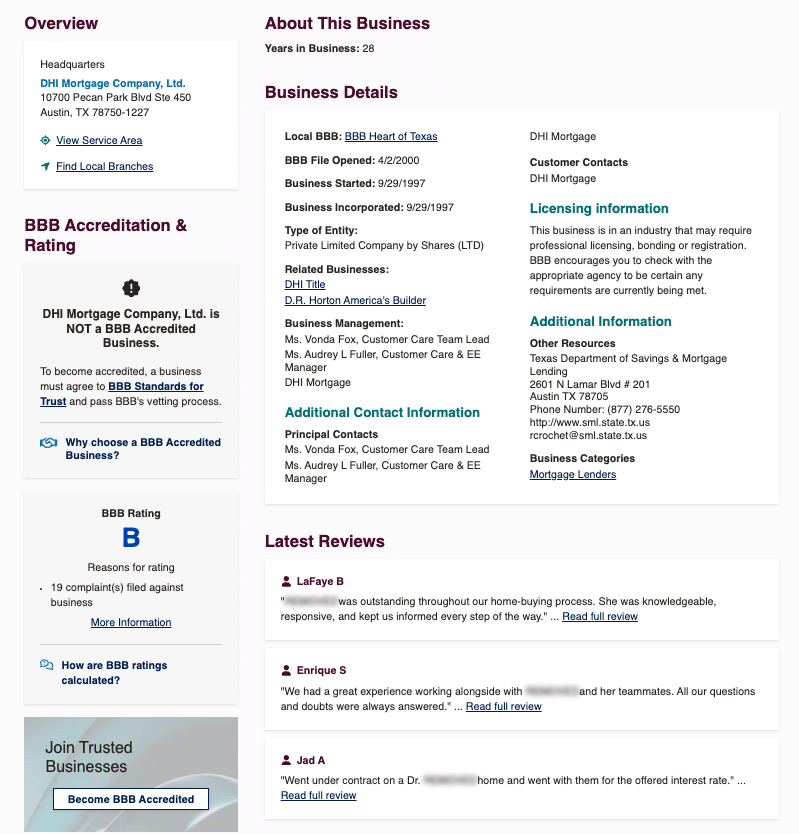
DHI Mortgage BBB profile
The BBB lists DHI Mortgage Company, Ltd. in Austin, Texas with a B rating and no accreditation. BBB records show 19 complaints filed in the last three years.
Customer reviews average 1.77 stars across 26 reviews. Recent posts cite escrow shock after closing and weak communication during the loan process.
Zillow reviews
Zillow does not publish one company-wide score for DHI Mortgage. It rates individual loan originators instead.
Many DHI Mortgage originators hold perfect or near-perfect profiles, including 5.0 and 4.97 ratings from dozens of reviews. The gap suggests service quality varies by loan officer.
Reddit reviews
In a July 2026 r/FirstTimeHomeBuyer thread, commenters told a buyer that DHI Mortgage loans are usually sold soon after closing. A locked rate stays intact, and only the payee changes.
Anything to know before closing? 4.875% with 800 scores and DR Horton financing. by u/Agreeable_Ad5620 in FirstTimeHomeBuyer
The same thread turned mostly to build quality, urging an independent inspection before closing and before the one-year warranty ends. One buyer flagged a year-two property tax jump once the home, not the empty lot, gets assessed.
A May 2024 r/FirstTimeHomeBuyer thread explained why outside lenders rarely match DHI Mortgage’s rates. One loan-officer moderator said D.R. Horton subsidizes the rate and profits from both the home sale and the loan. The thread added that D.R. Horton usually allows another lender with the same credits if DHI Mortgage declines approval.
Buyers in a November 2025 r/Mortgages thread weighed a 3.99 percent VA promo rate against credit-score overlays. Replies noted lenders use FICO scores, not Credit Karma numbers, and 680 generally clears most overlays.
Across all three threads, the recurring warning targets build quality and warranty follow-through, not loan terms. Commenters advise getting incentives in writing and hiring an independent inspector before closing.
CFPB complaints
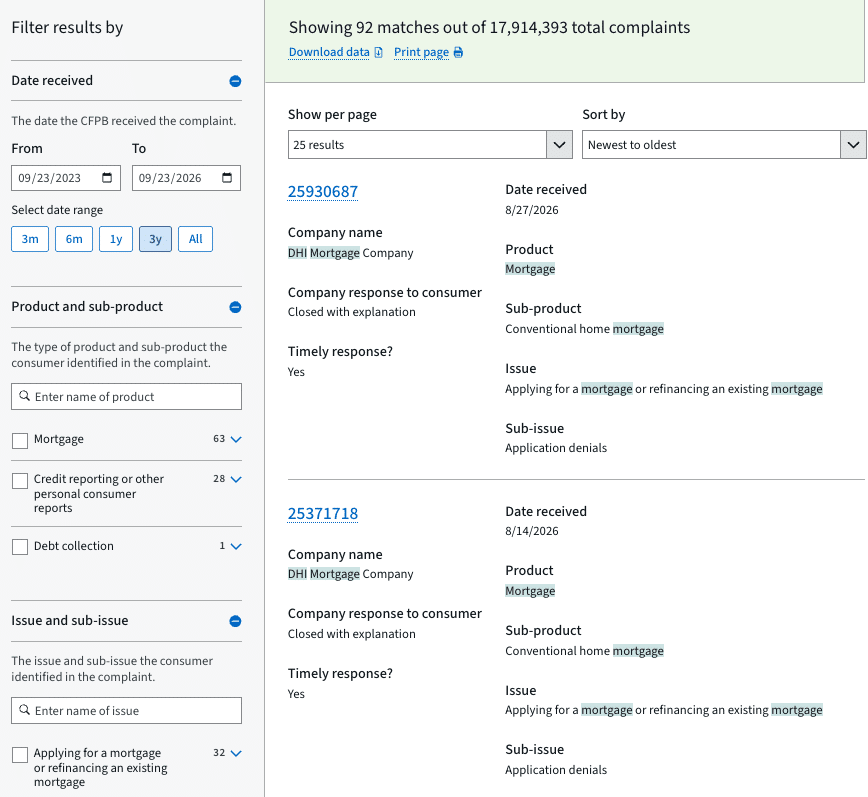
DHI Mortgage CFPB complaints
The Consumer Financial Protection Bureau (CFPB) complaint database shows 92 complaints naming DHI Mortgage in the past three years. Mortgage issues account for 63 of those complaints, and credit reporting accounts for 28.
The most common issue involves applying for a mortgage or refinancing, with 32 complaints. Recent complaints were closed with an explanation, and the company answered on time.
DHI Mortgage pros and cons
DHI Mortgage rewards convenience but carries service and legal risk.
Pros
- Financing, title and insurance under one roof can simplify a D.R. Horton purchase
- Rate buydowns and closing-cost credits can lower both upfront and monthly costs
- Credit-challenged buyers get a structured path through the Home Buyers Club
- Many individual loan officers hold perfect or near-perfect customer scores on Zillow
- Online tools let buyers start an application and estimate payments before committing
Cons
- A proposed nationwide class action over property tax estimates remains unresolved
- Company-level review scores are weak on WalletHub and BBB
- Loans move to outside servicers after closing, which shifts where payment issues go
- No public rate sheet means pricing requires a written quote to evaluate
- Incentive packaging can pressure buyers to skip outside comparisons
Who DHI Mortgage is best for
- D.R. Horton buyers who verified the post-construction property tax bill with the county assessor
- Shoppers holding a written quote they compared against an independent lender on the same home
- Credit-challenged buyers who understand the Home Buyers Club guarantees neither approval nor a higher score
- Long-term owners planning to stay several years while a new community builds out
Who should avoid DHI Mortgage
- Buyers relying on the quoted monthly payment without checking future property taxes
- Anyone who feels the incentive package leaves no genuine choice of lender
- Military borrowers who want a single point of contact fluent in VA documentation
- Buyers who expect the same company to service the loan after closing
Alternatives to consider alongside DHI Mortgage
Comparing outside quotes against DHI Mortgage’s incentive package gives buyers a fuller picture of the market. These three lenders may be worth considering.
Pulte Mortgage
Pulte Mortgage is the in-house lender for PulteGroup, making it the closest structural peer to DHI Mortgage. The company has financed more than 700,000 homes since 1972 and offers over 200 loan options.
Rocket Mortgage
Rocket Mortgage is a fully digital lender built around online applications. Purchase clients may qualify for a lender credit of 0.50 percent of the loan amount, up to $5,000.
VA buyers can purchase with no down payment, and first-time buyers can put down as little as 1 percent. A 1-0 temporary buydown is available in place of the lender credit.
Guild Mortgage
Guild Mortgage has operated for more than 60 years and lends coast to coast, except in New York. An in-house servicing team handles escrow and payoff questions after closing.
Borrowers may deal with the same company long after the loan funds. The lender also offers home equity products and a temporary buydown calculator.
Is DHI Mortgage legit?
DHI Mortgage is a licensed, operating lender, and buyers can confirm its record through NMLS Consumer Access. Legitimacy, however, is not the same as a clean record.
The class action remains an allegation in an active case, not a proven finding. D.R. Horton had not formally answered the core claims as of the latest 2026 reporting.
Review data points to real service problems at the company level, even as many individual loan officers earn top scores. Buyers should weigh the verified facts rather than hunt for a simple yes or no.
DHI Mortgage review verdict
Is DHI Mortgage legit? The verified record shows yes. Licensing and scale are real, and so are the complaints and the unresolved case.
DHI Mortgage reviews point in both directions, so the decision relies on verification. A confirmed tax bill, a competing written quote and a current case-status check settle the question for each buyer.
The next step belongs to the buyer. Remember to compare a written DHI Mortgage rate with at least one mortgage lender before signing anything.
DHI Mortgage frequently asked questions
What credit score do you need for a DHI Mortgage?
DHI Mortgage doesn’t publish a minimum credit score for its loans. Approvals may be near 680, and the Home Buyers Club works with buyers building toward eligibility.
Is it hard to get approved with a DHI Mortgage?
Approval follows standard mortgage documentation, with reported timelines ranging from a few days to a couple of weeks. Buyers with borderline credit can still enter through the credit-readiness program.
What are the closing costs for a DHI Mortgage?
DHI Mortgage closing costs vary by state, loan type and incentive package. The final closing costs may be near $6,900 on a $665,000 home.
Is DHI Mortgage a good lender?
Reviews are split between strong loan-officer experiences and company-level complaints. The answer depends on the individual officer and the checks a buyer completes before signing.
Published July 14, 2026; Updated September 22, 2026


Sponsored Advertising Content:
Advertorial or Sponsorship User published Content does not represent the views of the Company or any individual associated with the Company, and we do not control this Content. In no event shall you represent or suggest, directly or indirectly, the Company's endorsement of user published Content.
The company does not vouch for the accuracy or credibility of any user published Content on our Website and does not take any responsibility or assume any liability for any actions you may take as a result of reading user published Content on our Website.
Through your use of the Website and Services, you may be exposed to Content that you may find offensive, objectionable, harmful, inaccurate, or deceptive.
By using our Website, you assume all associated risks.This Website contains hyperlinks to other websites controlled by third parties. These links are provided solely as a convenience to you and do not imply endorsement by the Company of, or any affiliation with, or endorsement by, the owner of the linked website.
Company is not responsible for the contents or use of any linked website, or any consequence of making the link.
This content is provided by New Start Advantage LLC through a licensed media partnership with Inquirer.net. Inquirer.net does not endorse or verify partner content. All information is for educational purposes only and does not constitute financial advice. Offers and terms may change without notice.


