
Advertorial or Sponsorship User published Content does not represent the views of the Company or any individual associated with the Company, and we do not control this Content. In no event shall you represent or suggest, directly or indirectly, the Company's endorsement of user published Content.
The company does not vouch for the accuracy or credibility of any user published Content on our Website and does not take any responsibility or assume any liability for any actions you may take as a result of reading user published Content on our Website.
Through your use of the Website and Services, you may be exposed to Content that you may find offensive, objectionable, harmful, inaccurate, or deceptive.
By using our Website, you assume all associated risks.This Website contains hyperlinks to other websites controlled by third parties. These links are provided solely as a convenience to you and do not imply endorsement by the Company of, or any affiliation with, or endorsement by, the owner of the linked website.
Company is not responsible for the contents or use of any linked website, or any consequence of making the link.
LendingTree Reviews and Ratings
LendingTree Logo
LendingTree is a legitimate loan marketplace. But LendingTree reviews tell two very different stories, and you need to understand the gap before you apply.
Positive reviews praise fast offers and real savings. Negative reviews describe nonstop calls after you sign up. Both are real and show how the platform actually works.
So is LendingTree legit, and is it right for you? This review covers the ratings, real borrower feedback, and who should use it.
What is LendingTree?
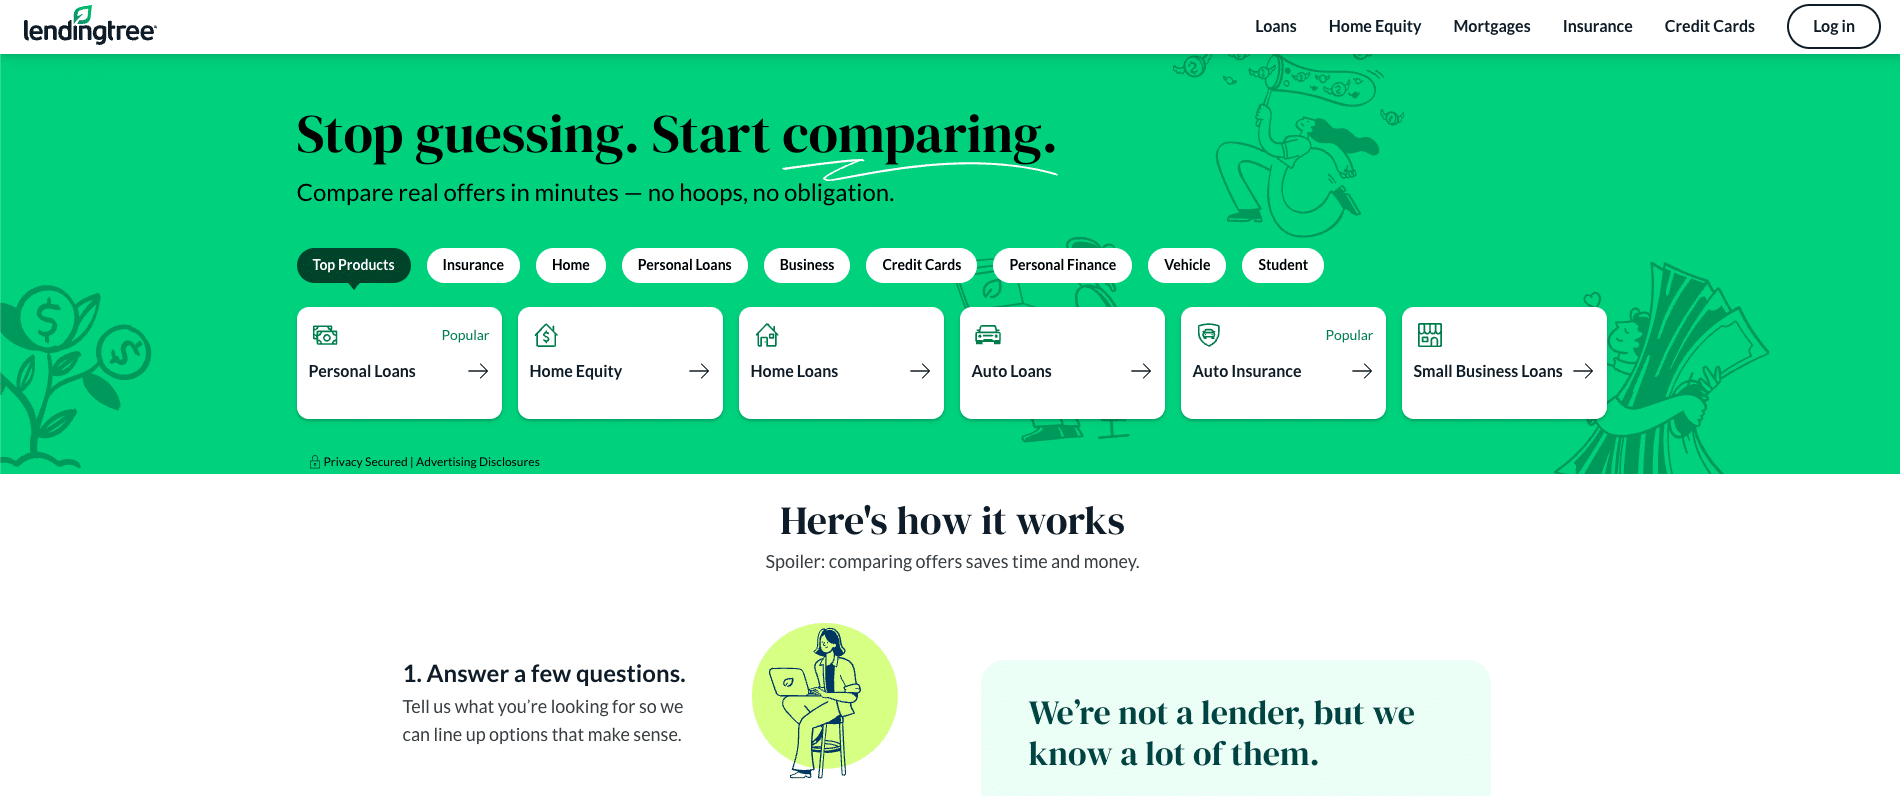
LendingTree website homepage
LendingTree is not a lender. It is an online loan marketplace founded in 1996 and headquartered in Charlotte, North Carolina.
The platform does not originate or fund loans. It matches you with lenders from its network so they compete for your business.
One form brings you offers across personal loans, mortgages, auto loans, home equity, credit cards, insurance and business loans.
The service is free for borrowers. Partner lenders pay LendingTree referral compensation when a match is made.
LendingTree at a glance
- LendingTree personal loans range: $1,000 to $50,000
- Loan terms: 24 to 84 months
- Starting annual percentage rate (APR): As low as 5.99 percent, up to 35.99 percent, depending on the lender
- Minimum credit score: 580 for most partners; some accept 300
- Best offers: 640 or higher
- Network: More than 300 lenders and 700 trusted partners
- Cost to borrowers: Free
- Founded: 1996, headquartered in Charlotte, North Carolina
- Public listing: NASDAQ under the ticker symbol TREE
- License: NMLS number 1136
- Track record: $297 billion in loans funded, 149 million people helped



How LendingTree works
LendingTree describes its process in three moves: answer a few questions, compare your offers and choose the winner.
The process is free and obligation-free.
- Answer a few questions. Go to LendingTree, select your loan type and enter the loan amount, purpose, estimated credit score, income and employment status.
- Marketplace screening. LendingTree runs a soft credit check to match you with partner lenders. Your score is not affected at this stage.
- Compare your offers. LendingTree loan offers arrive by email, usually within minutes. Compare APR, loan terms and origination fees side by side.
- Choose the winner. Some partners may reach out to sharpen their offers. You select the one that works for you and complete the full application directly with that lender.
- Final verification. The lender runs a hard credit pull at this stage. A slight, temporary score decrease of five points or fewer may occur.
- Funding. Timelines for LendingTree loans vary by lender. Same-day funding is possible if you sign before the cutoff, often 2:30 p.m. Eastern Time. Most borrowers receive funds within one to three business days.
Does applying to LendingTree hurt your credit score?
No, not at the comparison stage. LendingTree uses a soft credit pull, so shopping for offers has zero score impact.
A hard pull happens only when you formally apply with your chosen lender. Expect a temporary dip of five points or fewer.
Tip: Apply within a 14- to 45-day window. Most scoring models count rate shopping for mortgages and auto loans as one inquiry.
What loan types are available through LendingTree?
LendingTree covers seven categories: personal loans, mortgages, auto loans, home equity, credit cards, insurance and business loans.
Personal loans reach up to $100,000. Most are unsecured, so no collateral is needed. Some partners offer secured options for lower rates or easier approval.
Most offers are fixed-rate. Your rate and monthly payment stay the same for the life of the loan.

LendingTree pricing and fees
LendingTree has no application fees, no matching fees, and no membership costs. Using the marketplace is completely free.
The company gets paid by its partners. Its own disclosure states it “is compensated by companies whose listings appear on this site.”
This compensation may influence the order of offers you see. The lender absorbs this cost, not you.
Partner lenders charge their own fees, and these vary widely:
- Origination fees: Zero to 9.99 percent of the loan amount, depending on the lender. On a $15,000 loan, a 5 percent fee means $750 is deducted before funds reach you.
- No-fee options: Some lenders charge no origination fees.
- Prepayment penalties: Most partners do not charge them, but confirm before signing.
- Late fees: Vary by lender. Review the loan agreement before accepting any offer.
LendingTree rates and the reality of what borrowers expect
LendingTree does not set rates. Each offer comes from a matched lender based on your credit, income and debt profile.
Advertised rates sit near 6 percent, but those floors are reserved for the strongest borrowers. Most applicants see meaningfully higher offers.
Rates also shift with market conditions, so treat any published figure as a snapshot. The only reliable number is the one in the actual offer.
Should you apply with a co-borrower?
It depends on your credit. LendingTree allows joint applications, and several partners accept co-borrowers, including PenFed, SoFi, Upgrade and Prosper.
If your score is holding you back, a co-borrower with strong credit or higher income can improve approval odds and lower your rate.
Skip it if you qualify comfortably on your own. Co-borrowers share repayment responsibility equally, and missed payments hurt both credit scores. Joint applications also take longer, since lenders review two credit files.
Does LendingTree actually help with debt consolidation?
Yes, if your offers beat your current rates. A consolidation loan pays off your balances and leaves one monthly bill.
Borrowers with a score of 680 or higher typically beat the 24 percent average credit card APR.
Comparing matters. Users receive an average of 11 loan offers.
Watch for origination fees up to 10 percent on fair or bad credit. Lenders deduct fees before funds reach you.
Some lenders also offer direct pay, sending funds straight to your creditors, sometimes with a rate discount.
Lawsuits involving LendingTree
Here are the lawsuits involving LendingTree that borrowers should know about.
QuoteWizard data breach class action (pending)
In June 2024, hackers breached Snowflake’s cloud storage, which LendingTree and QuoteWizard used.
Exposed data included names, birth dates, Social Security numbers and financial information. QuoteWizard notified affected consumers on July 30, 2024.
Four users filed a proposed class action, now consolidated in Montana federal court as MDL No. 3126.
Claims include negligence, unjust enrichment and violations of Washington’s Consumer Protection Act.
Related cases against AT&T, Ticketmaster and other Snowflake clients are in the same MDL.
By October 2025, the court had denied LendingTree’s motion to force arbitration. The judge ruled its terms of use were not displayed conspicuously.
On August 19, 2026, the court ordered LendingTree to comply with Snowflake’s discovery demands.
The subpoenas cover its cybersecurity controls, the compromised account and customer communications.
LendingTree argued its appeal paused the proceedings. The court disagreed, since claims against Snowflake continue regardless.
$19 million texting settlement (resolved)
LendingTree made its final payment on a $19 million class-action settlement tied to QuoteWizard on July 31, 2026.
The case centered on the Telephone Consumer Protection Act (TCPA), which restricts unsolicited telemarketing calls and texts.
New texting class action (filed July 2026)
Days before the settlement disclosure, a new proposed nationwide class action landed in California federal court.
It alleges LendingTree sent promotional texts without required caller identification. This suit also falls under the TCPA.
LendingTree pros and cons
Every loan marketplace involves tradeoffs, and LendingTree is no exception. The advantages are real, but so are the limitations.
Pros:
- Multiple competing offers from one form
- Free to use
- No credit impact while shopping
- Seven product categories in one place
- Same-day funding with some partners
- Co-borrowers accepted by several partners
- Direct pay to creditors available
- Free Spring app for credit monitoring
Cons:
- No guaranteed approval, rates or matches
- Immediate lender outreach after submitting
- Data retained under record retention laws
- Zero-offer submissions still collect your data
- Higher rates and fees below 680 credit
- $50,000 personal loan cap with most partners
LendingTree reviews and what borrowers report across every platform
Here’s what real borrowers report about LendingTree on Trustpilot, BBB, ConsumerAffairs and Reddit.
Trustpilot reviews

LendingTree Trustpilot profile
LendingTree holds a 4.5 TrustScore from over 17,000 reviews. About 81 percent are five stars, and 7 percent are one star.
The profile is claimed with a paid subscription, and many recent five-star reviews are from invited reviewers. LendingTree replies to 67 percent of negative reviews.
Positive reviews cite fast applications and funding within 24 hours. Many describe the matched lender’s service, not the marketplace.
One-star reviews report nonstop calls and texts immediately after submitting the form.
Better Business Bureau (BBB) reviews

LendingTree BBB profile
BBB lists two separate scores. The business profile holds an A+ rating, accredited since November 2019, reflecting complaint responsiveness rather than customer satisfaction.
The customer review score is 1.05 across 94 reviews. Most complaints cite immediate lender outreach. One reviewer reported 12+ calls daily for a month.
Formal complaints total 166 over three years, with 55 closed in the past 12 months.
Some borrowers also dispute hard inquiries after clicking “View My Rates,” even though they expected only identity verification.
ConsumerAffairs reviews
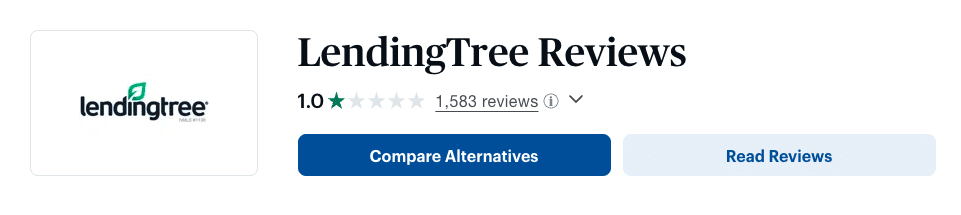
LendingTree ConsumerAffairs profile
ConsumerAffairs shows 1.0 from 1,583 reviews, last updated August 2026. One-star reviews make up 99 percent of rated feedback.
One June 2026 reviewer reported five to seven calls daily, nearly a year after a HELOC inquiry. Another counted 19 voicemails in 48 hours with no rate details.
Reddit reviews
LendingTree reviews on Reddit are unfiltered.
Is Lending Tree Legit? by u/Aubergine-Moth in povertyfinance
The r/povertyfinance community confirmed legitimacy in a May 2026 thread but doubted approval odds without paystubs. Commenters pointed the poster to local credit unions.
In July 2026, an r/HELOC homeowner reported dozens of calls within days. Replies shared similar stories lasting six months to over a year. Several said leads get resold to unrelated providers.
On r/loansharks, one thread reported 15+ calls in 48 hours. Many called advertised rates fictitious. Some described scam-like encounters with matched lenders, including upfront insurance fees.
Positive experiences exist. One user landed several loans with lower interest and no spam. Others said outcomes vary by loan type.
For those already flooded, threads point to LendingTree’s do-not-call page, which covers its affiliates. Credit unions and community banks remain the top recommended alternative.
LendingTree outcomes and success rate
Success on LendingTree depends on your credit profile. Stronger credit means more offers, lower rates and fewer fees. Weaker credit means fewer matches on less favorable terms.
The platform publishes marketplace data showing what borrowers actually receive by credit tier.
Borrowers with a score of 680 or higher consistently land rates below the average credit card APR. Below this threshold, savings shrink and origination fees become more common.
Approval is never guaranteed. LendingTree matches you with lenders, but each one applies its own underwriting criteria. Your income, existing debt and credit history decide the outcome.
Treat published figures as benchmarks, not promises. The only real measure of success is whether your actual offers beat your current rates.
How to stop LendingTree calls after applying
Start with LendingTree’s official do-not-call page at lendingtree.com/legal/do-not-call. It covers affiliates and takes 24 to 48 hours to process.
Then, contact each matched lender individually. LendingTree’s opt-out does not reach lenders already holding your data.
Expect limits. Record retention laws block full deletion. Resold leads mean some calls come from unrelated providers.
For future applications, use a Google Voice number or burner email. Blocking numbers helps only temporarily, since callers rotate through new ones.
Is LendingTree legit and safe?
Yes. LendingTree is legitimate, with 30 years in business, NMLS license 1136 and a NASDAQ listing. Its BBB profile holds an A+ rating, accredited since November 2019.
Is LendingTree safe with your data? The answer needs nuance. Submitting the form shares your data with matched lenders by design.
Who should use LendingTree?
Here is who LendingTree works best for and who should look elsewhere.
Best for:
- Borrowers with 680 or higher credit seeking competing offers fast
- Consumers consolidating $5,000 to $50,000 in high-interest debt
- Homeowners comparing mortgage or HELOC rates
- Buyers checking auto loan options before visiting a dealership
- Anyone comfortable managing follow-up lender contact
Not recommended for:
- Borrowers below 580, where matches thin out and rates climb
- Privacy-sensitive users who cannot manage heavy outreach
- Anyone needing more than $50,000 from most partners
- Borrowers who expect their data deleted on request
- Credit union members, whose rates often beat marketplace offers
LendingTree vs. going directly to a lender
Go direct if you know your lender and have strong credit. You skip the marketplace and its follow-up contact entirely.
Choose LendingTree if you are unsure which lender fits. Multiple competing offers give you comparison leverage a single application cannot.
Both paths have a full application with your chosen lender. The only question is how much comparison you want first.
LendingTree vs. other loan marketplaces
Each platform differs in network size, product coverage and how user data is handled.
Borrowers can consider Credible, Bankrate or NerdWallet alongside LendingTree before deciding.
- Credible shows real prequalified rates, not estimates. It shares data with lenders only with your permission and pledges no spam calls. Its product range is narrower, focused on loans and insurance.
- Bankrate is mortgage-first, with 100+ lenders competing on home loans. Your information stays private until you decide to apply. Founded in 1982, it also supplies rate data to the Federal Reserve.
- NerdWallet leads on education, with 15,000+ resources and 100+ experts. Its app tracks net worth and offers a cash account, but matching depth is thinner.
Final verdict: Is LendingTree worth it?
So how good is LendingTree, really? This LendingTree review comes down to one question: how much comparison do you want before your data goes out?
LendingTree works as a comparison tool: one form, multiple offers, no fee, no credit impact while shopping. In exchange, matched lenders receive your contact information, and outreach follows.
Borrowers who completed loans report strong outcomes. Those seeking only information usually report frustration.
If comparison speed matters most, LendingTree serves that. For data control, it might be best to apply directly.
Frequently asked questions about LendingTree
Is LendingTree a good company to get a loan from?
Yes, if your goal is comparing multiple offers quickly. The loan itself comes from a matched lender, not LendingTree.
Does LendingTree do a hard pull on your credit?
No. Checking offers uses a soft pull, and a hard pull happens only when you apply with a chosen lender.
Does LendingTree sell your info?
Yes. Its 2026 privacy notice confirms selling and sharing identifiers, browsing activity and geolocation data with advertising partners.
Opt out through the “Your Privacy Choices” link in its website footer or by calling 1-800-505-7916.
Does LendingTree ask for your bank login information?
No. The form asks for income, employment and credit range, never bank credentials.
Is LendingTree hard to get approved?
Not with a 680 score or higher. Most partner lenders start at 580, and approvals improve with stronger credit.
Published April 10, 2026; Updated September 15, 2026


Sponsored Advertising Content:
Advertorial or Sponsorship User published Content does not represent the views of the Company or any individual associated with the Company, and we do not control this Content. In no event shall you represent or suggest, directly or indirectly, the Company's endorsement of user published Content.
The company does not vouch for the accuracy or credibility of any user published Content on our Website and does not take any responsibility or assume any liability for any actions you may take as a result of reading user published Content on our Website.
Through your use of the Website and Services, you may be exposed to Content that you may find offensive, objectionable, harmful, inaccurate, or deceptive.
By using our Website, you assume all associated risks.This Website contains hyperlinks to other websites controlled by third parties. These links are provided solely as a convenience to you and do not imply endorsement by the Company of, or any affiliation with, or endorsement by, the owner of the linked website.
Company is not responsible for the contents or use of any linked website, or any consequence of making the link.
This content is provided by New Start Advantage LLC through a licensed media partnership with Inquirer.net. Inquirer.net does not endorse or verify partner content. All information is for educational purposes only and does not constitute financial advice. Offers and terms may change without notice.


